The situation we see most often
Prospective and new clients often engage us after certain investments have already been made for the benefit of a U.S. business — and they want those expenditures to count as evidence of being “in the process of investing” for the E-2 treaty investor visa. A common variation of the question: do payments for goods, equipment or inventory made from the investor’s personal bank account qualify?
What a consular officer actually assesses
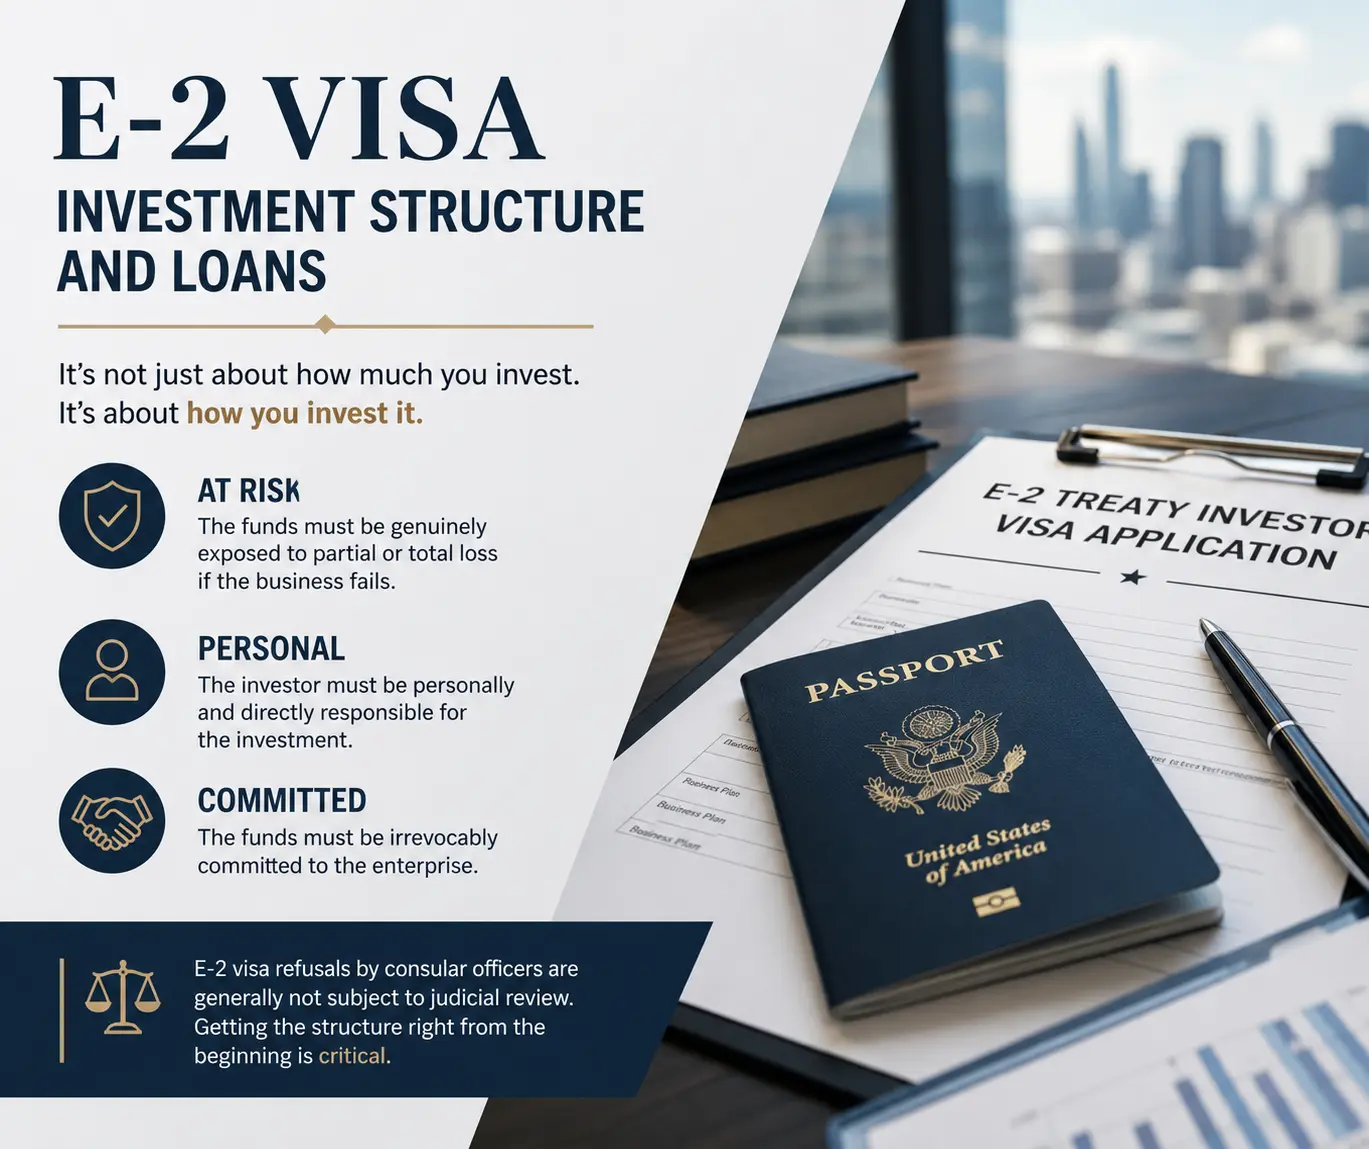
The Foreign Affairs Manual instructs officers to assess “the nature of the investment transaction” — not just the amount (9 FAM 402.9-6(B)). Three core criteria run through the analysis:
- Source, possession and control. Funds may come from savings, gifts, inheritance, loans collateralized by the applicant’s personal assets or other legitimate sources — but the applicant must demonstrate possession and control, and the source must not be illicit.
- Risk. “The concept of investment connotes the placing of funds or other capital assets at risk, in the commercial sense, in the hope of generating a financial return.” Money that cannot be lost if the business fails is not an investment in the E-2 sense.
- Irrevocable commitment. The funds must be committed to the enterprise, and the commitment must be real and irrevocable — funds simply sitting in an account are not yet “invested”.
So can personal-account payments count?
It depends on the details — but yes, they can. The ideal scenario is clean: the investor transfers funds directly to the bona fide U.S. enterprise, and every subsequent purchase is made from the company account. That produces a paper trail an officer can follow in minutes.
Payments made from the investor’s personal account may still qualify as part of the investment if the purchased goods, equipment or inventory are transferred to and used by the U.S. enterprise. The burden is on the applicant: you must show, with strong documentation, that the expenditures were for the enterprise — not for personal use.
Documentation that carries that burden
- Invoices and receipts that identify the item, the seller and the price;
- Bank statements matching each payment to a specific purchase;
- Evidence the items were transferred to the company (transfer agreements, capital-contribution records, company books reflecting the assets);
- Evidence the company actually uses the items (photos of premises, inventory records, the business plan describing the equipment’s role).
What does not count
- Personal living expenses of the investor or their family;
- Funds that remain in the investor’s personal account, however substantial;
- Cash purchases with no documentary trail linking them to the enterprise.
Order of operations matters
The investment structure is easiest to fix before the money moves. If you are planning an E-2 case, the safest sequence is: consult, structure the accounts, then invest — see also our analysis of what actually causes E-2 refusals and when borrowed funds become a problem.
How RegattaLex can help
A free introductory call with a California-licensed attorney to review your investment structure before filing. Flat, published fees. Start with the E-2 eligibility check.
This article is for general information only and is not legal advice.